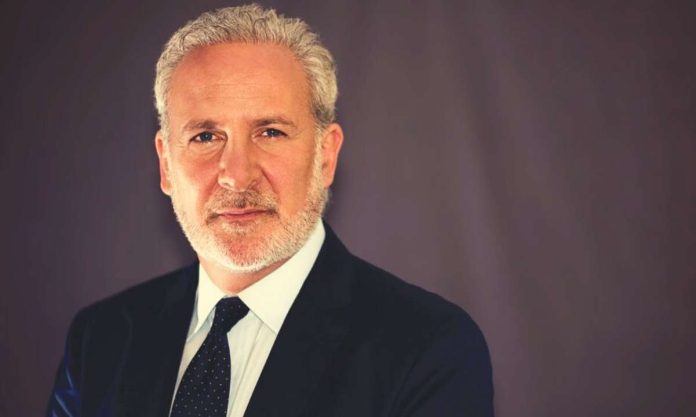
In a rare public divergence from his usual skepticism of digital assets, economist Peter Schiff pushed back against JPMorgan Chase CEO Jamie Dimon’s insistence that stablecoin issuers be subjected to the same capital and compliance frameworks that govern traditional banks. Schiff’s comments, posted on X on June 7, challenged Dimon’s view that interest‑bearing stablecoin products should be treated as de‑facto bank deposits, arguing that the structural differences between the two sectors render such parity unnecessary—and potentially counterproductive.
Schiff’s rebuttal began with a straightforward distinction: banks operate under a fractional‑reserve model, benefit from FDIC insurance, and extend credit that can amplify systemic risk. Stablecoin issuers, by contrast, typically hold reserves composed of cash or short‑term government securities, and many—such as those backing USDT or USDC—claim 100% backing by liquid assets. Schiff emphasized that when a stablecoin is fully collateralized by Treasuries and does not engage in lending, the prudential rationale for imposing bank‑style capital buffers evaporates.
The economist’s stance is notable given his long‑standing criticism of crypto’s perceived lack of investor protection. In response to a follower who pointed out the apparent contradiction, Schiff clarified that his objection is not a blanket endorsement of all crypto activity but a recognition that certain stablecoin designs serve a functional purpose akin to digital cash. He argued that imposing blanket banking regulations on these tokens would stifle innovation without delivering commensurate safety gains.
Dimon’s push for stricter oversight emerged during a late‑May interview where he criticized the CLARITY Act, a bipartisan bill advancing through the Senate Banking Committee. The legislation seeks to clarify the regulatory treatment of stablecoins, particularly those that offer yield. Dimon warned that allowing crypto firms to pay interest on stablecoin holdings would create a regulatory arbitrage, enabling entities to reap bank‑like returns while bypassing anti‑money‑laundering (AML) safeguards and capital requirements. He also took aim at Coinbase CEO Brian Armstrong, a vocal proponent of the bill, labeling his advocacy as disingenuous.
Supporters of the CLARITY Act, including Senator Cynthia Lummis, countered that Dimon’s characterization misreads the bill’s text. They noted that the legislation actually extends existing Bank Secrecy Act provisions to digital assets, thereby strengthening AML controls rather than weakening them. Lummis suggested that Dimon’s opposition may stem from either a lack of familiarity with the bill’s details or a strategic effort to sway public opinion against a measure that could erode traditional banks’ dominance in the payments arena.
The debate is set against a backdrop of intensified lobbying from the banking sector. In the weeks preceding the Senate Banking Committee vote, the American Bankers Association dispatched over 8,000 letters to Senate offices urging amendments to the stablecoin yield provisions. Simultaneously, the Bank Policy Institute highlighted a sharp rise in illicit crypto flows, citing a 162% increase to $154 billion in 2023, with stablecoins—predominantly Tether’s USDT—accounting for 84% of suspicious transaction volume. These figures have been used to argue for tighter oversight, though critics contend that the data conflates legitimate usage with illicit activity and fails to differentiate between various stablecoin models.
From a policy perspective, the clash underscores a fundamental tension: how to harness the efficiency gains of blockchain‑based money while mitigating risks to financial stability and preventing illicit use. Schiff’s intervention adds a nuanced voice to the conversation, reminding regulators that not all stablecoins are created equal and that a one‑size‑fits‑all approach could impede legitimate use cases such as cross‑border remittances, programmable payments, and decentralized finance (DeFi) infrastructure. As the Senate deliberates the final shape of the CLARITY Act, the outcome will likely hinge on whether lawmakers adopt a risk‑based framework that distinguishes between fully backed, non‑yield‑bearing stablecoins and those that incorporate lending or interest‑generation mechanisms.