
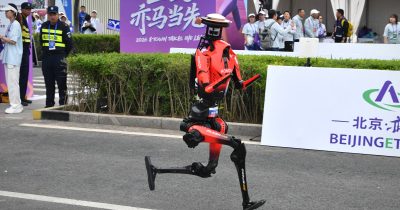
China has established an overwhelming lead in the humanoid robotics sector with domestic manufacturers now controlling ninety seven percent of worldwide shipments according to recent industry data. This remarkable concentration of production capacity represents more than just a manufacturing milestone it signals a fundamental restructuring of global automation economics that will reverberate across supply chains for decades to come.
The implications extend far beyond factory floors as humanoid robots increasingly integrate with blockchain based tracking systems and decentralized finance protocols that manage automated production workflows. Smart contracts now coordinate maintenance schedules parts procurement and quality verification across distributed manufacturing networks while tokenized assets represent fractional ownership in robotic fleets operating across multiple jurisdictions.
Labor demographics drive much of this acceleration as China faces one of the most rapid workforce contractions in modern history. The working age population has declined for twelve consecutive years creating an existential imperative for automation that Western economies will confront with a decade of delay. Chinese policymakers have responded with targeted subsidies research grants and regulatory frameworks that treat humanoid robotics as strategic infrastructure rather than consumer technology.
Key players including Unitree Robotics Fourier Intelligence and UBTECH have achieved production scale that allows iterative improvement cycles measured in weeks rather than quarters. Their robots now perform complex assembly tasks in automotive plants handle hazardous materials in chemical facilities and provide elder care services in pilot programs across tier one cities. Each deployment generates terabytes of operational data that feeds back into foundation models improving dexterity reasoning and safety protocols.
The blockchain integration layer deserves particular attention as it solves coordination problems that previously limited robotic fleet management. Immutable ledgers track component provenance from raw materials through final assembly enabling instant recall capabilities and regulatory compliance verification. Decentralized oracle networks feed real world sensor data into smart contracts that automatically trigger maintenance orders insurance adjustments and performance based payments to robot operators.
Western competitors face structural disadvantages that policy interventions cannot easily overcome. The Chinese ecosystem benefits from vertically integrated supply chains where motor manufacturers sensor producers and AI researchers share physical proximity and cultural alignment. This density enables rapid prototyping and reduces the friction of translating laboratory breakthroughs into production ready systems. American and European firms increasingly rely on Chinese components despite strategic efforts to diversify.
Investment flows reflect this reality as venture capital allocates disproportionately to Chinese robotics startups despite geopolitical tensions. The tokenization of robotic assets through security token offerings and real world asset protocols creates novel capital formation mechanisms that bypass traditional banking channels. These financial innovations accelerate deployment cycles by allowing fractional investors to fund specific robotic units and share in their operational revenue streams.
Regulatory divergence adds another layer of complexity as China develops certification standards for humanoid robots that may become de facto global benchmarks through sheer market dominance. International standards bodies struggle to keep pace with capabilities that evolve monthly rather than annually. This regulatory asymmetry could lock in Chinese technical approaches for safety human robot interaction and data governance across international markets.
The convergence of humanoid robotics blockchain infrastructure and decentralized finance represents a new paradigm for physical world automation. As these systems mature they will reshape not just manufacturing but logistics healthcare construction and domestic services. The ninety seven percent shipment figure captures a moment in time but the underlying dynamics suggest China’s lead will widen before it narrows creating opportunities and challenges for every participant in the global technology economy.

